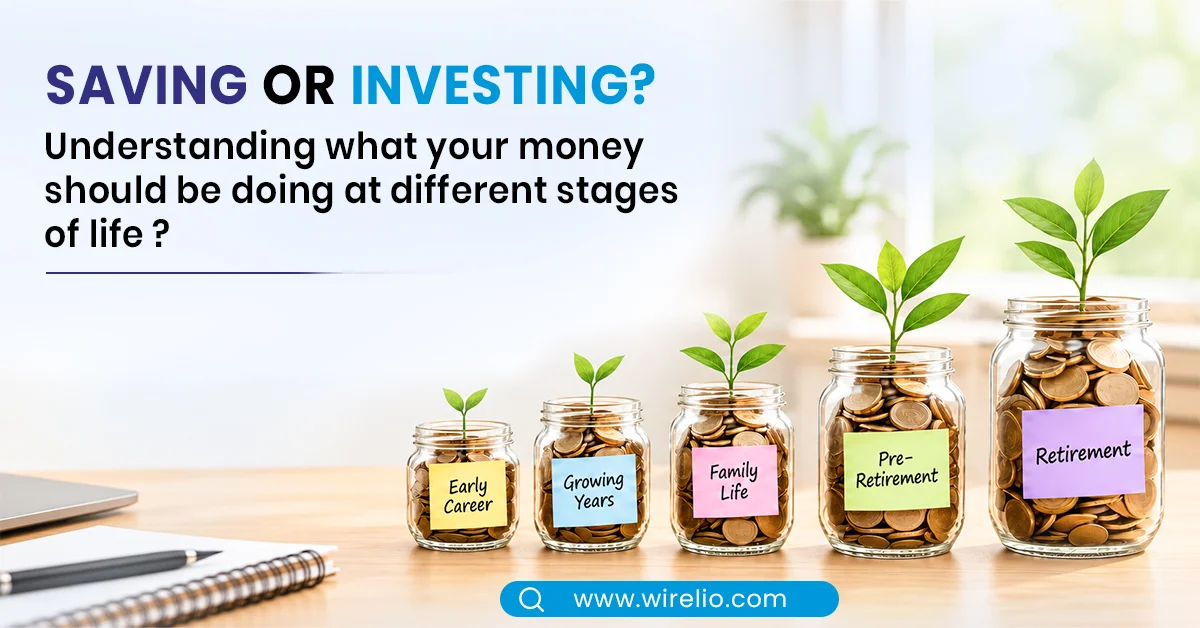
Saving and investing are two words that are very often used in the context of managing finances. However, many people are not completely sure what the difference between these two concepts is.
Should you rather save or invest your money? How much money should you save for a rainy day and how much should you invest? Does it even matter?
The answer is, it does.
Saving and Investing: The Difference Explained
Below you can see the primary difference between saving and investing.
Saving = keeping the money available for your near future expenses (almost any time you might need it).
Investing = putting your hard-earned cash to work for you (in long-term goals, but with a certain level of risk).
In other words, saving is like having an umbrella in the back seat of your car – you never know when you might need it, so it is best to always have one within reach. Whereas, investing is like planting a tree – you do not expect it to become an oak in a few days, but you know that one day you will need shade and a place to sit.
Both actions are very necessary in human life, but they serve absolutely different purposes.
Saving | Investing |
| Usually meant for short-term needs | Generally meant for long-term goals |
| Focuses on accessibility and capital safety | Focuses on potential growth |
| Usually involves lower risk | Can involve higher risk |
| Useful for emergencies | Useful for long-term wealth creation |
| Money is generally easier to access | Investments may fluctuate in value |
| Suitable for upcoming expenses | Suitable for longer-term financial goals |
Why Do You Need Both Saving and Investing?
Let's say you invest all your money.
Then your phone gets damaged, you have a random expense, or an emergency comes up. You might have an investment, but it might not be in the form or time-frame that you might need it in.
Or say that you saved all your money for decades. You might easily have access to it, but your savings might not grow for the long-term. That's why it's not so much important to know what you do with your money.
It's more important to know when to do it.
Stage 1: The Student — Learn the Habit of Saving
At this age, the most important thing is to understand the habit of saving. You might not have a source of steady income.
But that doesn't mean that you can't start saving early in life. At this age, the focus should be less on the money you save and more on the habit.
While building up this habit, the money you save might come from pocket money, any part-time job income, your internship, scholarship, freelancing, and gifts.
pocket money, any part-time job income, your internship, scholarship, freelancing, gifts
There is no rule about needing to have a certain amount of money before you can start saving. Having a small amount of money saved can make all the difference.
To understand investing, you also need to see how to make money grow. But at this stage, focus only on the habit of saving money.
What should that money be used for?
The primary focuses at this stage would be:
- Learning to save money
- Understanding the basics of personal finance
- Avoiding lifestyle inflation and taking extra debts
- Learning the idea of interest and inflation
- Making small savings goals
If you're earning money at this time, you can start learning about investing through some regulated methods rather than going right into investments just because it sounds cool.
Stage 2: Your First Job — First Build a Safety Net
Now, suddenly, you're earning money, and everything looks so glamorous! But before you start investing your earnings in non-essential things at this point, you should set up an emergency fund.
An emergency fund is the money that you save for situations including, but not limited to medical crises or personal emergencies, emergency travel, loss of income, house maintenance problems, anything else unforeseen.
To better understand on how to manage your salary, check out our blog here!
Your emergency fund would vary from person to person depending upon the following your income, expenses, responsibilities. But it's important to know that your long-term finances should not be your first line of defense in the face of any disaster.
Start investing when you've built up your financial safety net and can clearly see your financial requirements. The time-value of money allows you to make small investments grow exponentially over long periods of time.
Stage 3: Your 20s and Early 30s — Balance Your Lifestyle Inflation
This stage in life is extremely hectic because this is when you start becoming independent.
You may have a better income, but with the following lifestyle inflation higher rent, vacations, more expenses, family demands, student loans, a car loan, a plan to get married, a plan to get a house, and a plan for the long-term future.
It becomes an easy out to say, "I will start investing when my income rises."
But your income isn't the only thing that needs to rise. As your income rises, so should your ratio of income that goes into saving and investing.
When your salary increases, it doesn't mean that your entire salary increase has to go into more discretionary expenses.
You could divide your increased salary into the following:
- Savings
- Investments
- Lifestyle expenses
- Some for the short-term goal
In case all this doesn't apply specifically to you, then it's time ask yourself if it's because your salary still doesn't justify making those changes.
Stage 4: The Long Road Ahead — Assign Every Rupee a Task
At the beginning of your work life, your goals were quite broad: buy a house, get married, take care of kids, retire, and so on. Each of these goals needs different financial requirements.
A home requires a lump sum when purchased, so it might be the easiest investment goal for you to plan out. Marriage and the associated costs, if you're expecting it to land in your lap in the near future, will need an allocated financial amount and a specific destination for its investment.
The same goes for children's education, which is more of a long-term investment horizon, but still one that you needn't put all your money into at once.
Retirement seems like a century from now when you're young and full of life, but it is one of the biggest reasons long-term investment horizons like equity are suggested at an early age.
The main point is to understand that different goals need different approaches. A short-term financial requirement won't benefit you as much from long-term market fluctuations.
For long-term goals, however, there is more scope to work with a volatile market depending on your risk-taking capacity.
Saving for a Short-term Goal vs. Investing for a Long-term One
The easiest way to differentiate between a short-term and long-term financial goal is to see their time durations.
Say, you need 1 lakh for an expense that you know of 6 months from today.
It is a short-time goal, and it's more likely that the value of that amount might depreciate before you reach your goal if held in a volatile instrument. On the other end of the spectrum, there's your retirement money that will be in the market for 40 years.
This is one of the reasons why time horizon becomes such an important deciding factor for your money before you begin investing. One easy rule of thumb is to put aside money that you may need fairly soon in easily accessible and liquid funds. For money that you will not need for much longer, you can take calculated risks to make it grow.
What About Emergency Fund?
The emergency fund is actually fairly important and falls in between liquid and long-term funds. You shouldn't really aim to grow that fund, but instead have enough money to get you through any financial shortfall.
The size of an emergency fund varies from person to person depending upon their annual income and their liabilities and responsibilities.
Someone who has an unstable income from their primary occupation but a more stable supplemental one and also has dependents will need a bigger emergency fund than someone who has the reverse of that situation.
Check out tips on how to manage everyday payments here!
What Is Compounding and Why Should I Know About It?
Compounding is one of the biggest pillars of investment that you must understand early in your journey.
In layman's terms, compounding means that the returns earned from your investment can go back into the pool for further profit generation. The snowball effect of compounding is what makes it so important to start investing as early as possible.
Even a smaller amount invested on a regular basis for a long time has a very good chance of beating lump sum amounts at later times when you might think it is a good time to invest. This is not to suggest that you should invest amounts recklessly in anticipation of compounding, as it's possible that you could have made greater returns in a lower-risk scheme over a shorter time.
Savings Don't Mean Buried Cash Under Your House
When it comes to the idea of saving money, most people tend to think that a stash of cash hidden under a mattress is what it's all about.
The reality is that there are a variety of safe and suitable options for saving money. The idea is to know what kind of a safety net and accessibility you require to meet your savings objectives. For instance, the money that you will need immediately in case of an emergency should not be treated the same way as retirement money that you can save for decades.
Investing Doesn't Mean Chasing Markets
One popular misconception about investing is that it means going out and finding the next hot stock tip. That's akin to gambling, not investing.
To invest, you allocate some amount of money into a financial instrument that will hopefully make you money in the long term.
Based on your investment requirements, that could be any number of instruments like mutual funds, stocks, bonds, exchange-traded funds, or just other financial instruments.
mutual funds, stocks, bonds, exchange-traded funds, or just other financial instruments
Each of these carry varying weights of risk, complexity, and reward. It is important for beginners to familiarize themselves with the fundamentals of an investment tool before jumping in solely because someone else suggested it on social media.
Common Mistakes Made by Novice Investors
1. They start investing before creating a financial cushion
2. Putting all the money in the safe place and leaving it there
3. Investing just because everyone else is
4. Failing to account for inflation
5. Mistaking speculation for investing
6. Waiting for the right moment
Learning about investing and putting small amounts of money at risk is a much safer alternative to waiting for the perfect time to invest.
Investing Tips for Novice Investors
Do not overthink the matter if you are a complete novice when it comes to finance. Ask yourself these four questions, and you will be well on your way to learning how to make money out of money. First, what money do you need to have liquid at all times? This is money that can come to your aid immediately if you need it. A small emergency fund is a good idea for everyone to have.
Next, do you have an emergency fund? If not, then that is a priority. Then, think about your long-term goals. What are you trying to achieve in life? Do you want to retire early, buy a house, or send your children to college? The money you save should be directed toward achieving your goals.
Finally, how much risk are you willing to undertake? A stock that makes you lose sleep at night is not a good candidate for a long-term investment, regardless of how attractive its prospective yield might be.
Frequently Asked Questions: Saving vs Investing
1. What is the difference between saving and investing?
Saving generally means keeping money accessible for short-term needs and financial emergencies, while investing involves putting money into assets with the goal of achieving potential long-term growth. Saving usually prioritizes accessibility and stability, whereas investing involves some level of risk.
2. Should I save money or start investing first?
For many beginners, building a basic emergency fund and managing high-interest debt can be important steps before putting significant amounts into long-term investments. Once you have a financial cushion, you can consider investing according to your goals, time horizon, and risk tolerance.
3. How much money should I keep in savings?
There is no single amount that works for everyone. Your savings needs depend on your monthly expenses, income stability, existing financial commitments, and upcoming expenses. An emergency fund should generally be sufficient to handle unexpected costs without forcing you to sell long-term investments.
4. When should I start investing?
You can start learning about investing as soon as you have an income and understand your basic financial needs. Starting early can give your investments more time to potentially benefit from long-term growth and compounding.
5. Is saving safer than investing?
Savings products designed for capital preservation and accessibility generally involve less market risk than investments such as stocks or equity-oriented funds. Investments can fluctuate in value, so the appropriate choice depends on your financial goal and how much risk you can comfortably accept.
6. What is an emergency fund and why is it important?
An emergency fund is money kept aside for unexpected expenses such as medical costs, sudden repairs, or a temporary loss of income. It can provide financial flexibility and reduce the need to borrow money or sell investments at an inconvenient time.

No comments posted yet. Be the first to express your thoughts!