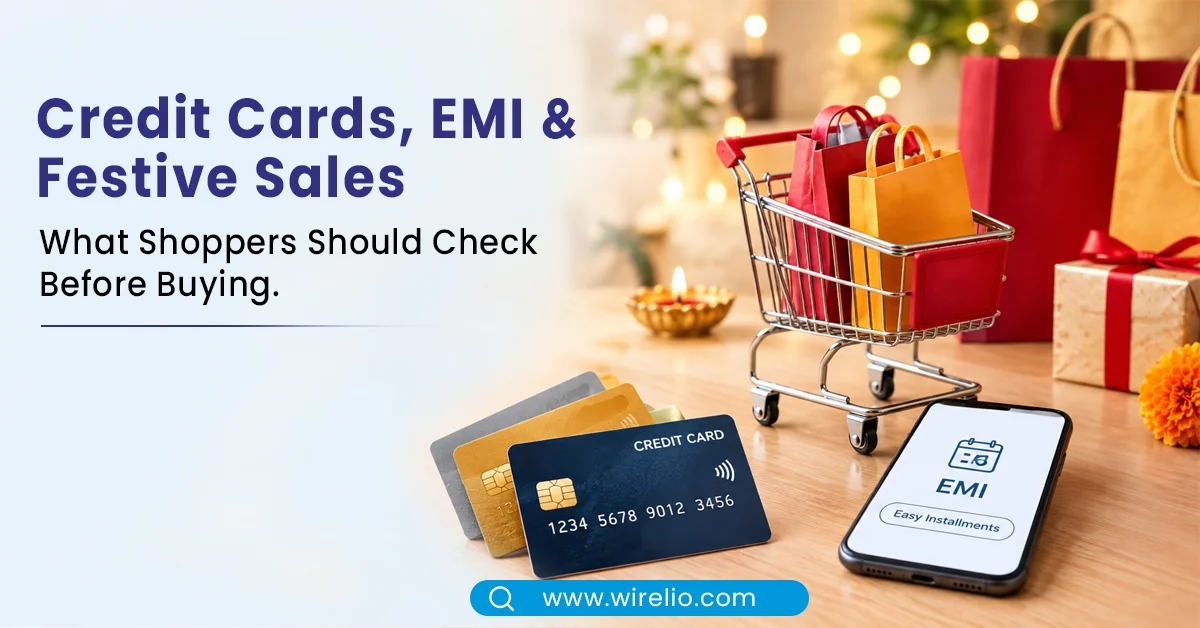
You have found the phone. You have found the sale price. The confusing part begins: "No-Cost EMI", "additional cashback", and what am I supposed to do?
If you have ever reached the payment page while shopping during a festive season and wondered if you need a credit card to avail of this offer, you are not alone.
Terms such as credit card, bank offer, EMI, No-Cost EMI, cashback and instant discount can sound complex when all you want is to buy a new smartphone or laptop.
The good news is, you don't need to be a banking expert to understand them.
Let's start with understanding each term in simple language so that the next time you land on a sale page, during a Diwali Sale, Great Indian Festival or Big Billion Days, you have a clear idea about the kind of offer you are availing of.
What Exactly Is a Credit Card?
A credit card can be thought of as a short-term loan facility from your bank.
Instead of the money in your savings account, the bank gives you an amount (up to a certain limit) which you can use to make eligible purchases and then pay back to your bank.
For example:
Say your credit card has a limit of Rs. 1,00,000.
You find a smartphone that costs Rs. 60,000 and decide to buy it.
On the payment page, instead of paying with your savings account, you pay with your credit card. The bank pays the amount to the merchant, and you owe them Rs. 60,000; this reflects in your credit card statement. You can then pay back the amount in accordance with the billing cycle and due date mentioned by the bank.
Remember, if you pay your billed amount in time, you will not be charged any interest on the payment.
So in summary, a credit card is: Buy now using your approved credit limit and repay the bank later.
Why Do Shopping Sites Give Credit Card Offers?
Now comes the fun part.
During a shopping holiday (yes, it really is fun to shop!), the shopping platform and the bank collude to give special offers to customers purchasing with eligible cards.
For example, you may see an offer on a smartphone that says: Rs. 50,000 and below it, 10% instant discount with eligible Axis Bank/ICICI Bank cards.
This basically means that the eligible card holder will pay Rs. 45,000, subject to the terms and conditions of the offer, including minimum order value and maximum discount.
Looking at Flipkart's current Big Billion Days 2026 page, for instance, you will see instant discounts on eligible Axis Bank and ICICI Bank card transactions, along with No Cost EMI and other payment options.
Credit Card vs Debit Card: What's the Difference?
This is another common confusion.
Credit Card | Debit Card |
| Uses a credit limit provided by the bank | Uses money available in your bank account |
| You repay the bank later | Amount is generally deducted from your account |
| Can have a billing cycle | No credit-card billing cycle |
| Can offer rewards/cashback | Can also offer rewards, depending on the card |
| Often eligible for special credit-card/EMI offers | Eligible only when the sale specifically includes debit cards |
So if a sale says:
“10% instant discount on eligible credit cards”
using your debit card may not qualify—even if both cards are issued by the same bank.
Always read the exact offer terms.
How Do Credit Card Offers Work During Festive Sales?
Let's say you've been waiting for a smartphone.
The phone's sale price is: Rs. 50,000
Now the product page says: 10% instant discount on eligible credit cards, up to Rs. 3,000
You have an eligible card.
You select the card payment option and complete the transaction according to the offer conditions. The discount could then be applied as specified by the offer.
But here's the important part: 10% does not always mean unlimited 10% savings.
There may be:
- Minimum purchase requirements
- Maximum discount limits
- Specific eligible cards
- Specific products
- Specific payment methods
- Offer validity periods
- Transaction limits
- EMI-only conditions
- Exclusions on certain categories
For example, Axis Bank's published Flipkart offer terms show that some offers have minimum transaction values and maximum discount limits, and eligibility can vary by card type.
So don't just look at the big “10% OFF” label. Open the offer details before paying.
What Is an Instant Bank Discount?
This one is actually pretty straightforward.
An instant discount means the eligible discount is applied as part of the transaction according to the offer terms.
Example:
Smartphone price: Rs. 50,000
Eligible bank offer: 10% instant discount
Potential discount: Rs. 5,000
Effective price: Rs. 45,000
But remember: if the offer says 10% discount up to Rs. 2,000, your saving is Rs. 2,000—not Rs. 5,000.
This is one of the biggest mistakes shoppers make during sale season.
What Is Cashback?
Cashback is slightly different. Instead of necessarily reducing the product price immediately, a cashback offer gives you money/value back according to the card or offer's rules.
For example:
You spend Rs. 20,000.
Your card offers 5% cashback.
You may receive Rs. 1,000 cashback, subject to the card's eligibility, exclusions and cashback limits.
The cashback could appear later in your card statement or as another form of reward, depending on the card.
Instant discount vs cashback
Instant discount:
Your payable amount may reduce during checkout.
Cashback:
You pay according to the transaction and receive the cashback later according to the offer/card rules.
This distinction is important when you're comparing two deals.
What Is EMI?
Now let's tackle the word that appears everywhere during festive sales:
EMI.
EMI stands for Equated Monthly Instalment.
Instead of paying the entire purchase amount at once, you repay it in smaller instalments over a fixed period.
For example, imagine a smartphone costs: Rs. 60,000
Instead of paying Rs. 60,000 at once, you may have an option to divide the purchase into monthly payments over a selected tenure.
Depending on the EMI plan, interest and processing fees may apply.
So: EMI = Divide the payment into scheduled monthly instalments.
What Is No-Cost EMI?
This is where things get interesting.
No-Cost EMI generally means the customer is offered an EMI structure where the interest cost is offset through an upfront discount or other arrangement, so the advertised EMI effectively doesn't add the usual interest cost.
But don't assume that “No Cost” = “Absolutely no additional cost under every circumstance.”
The actual offer can have processing fees, GST or other applicable charges depending on the transaction and provider.
RBI rules require card issuers to clearly disclose the principal, interest and any upfront discount used to make an EMI “no cost” before conversion, and these components should also be shown in the statement.
Simple example
Suppose a phone costs: Rs. 60,000
The website offers a 6-month No-Cost EMI.
Instead of paying Rs. 60,000 upfront, you may pay approximately:
Rs. 10,000 × 6 months
subject to the actual EMI calculation and applicable charges.
That's why you should always check the total amount payable, not just the monthly EMI displayed in large text.
Can You Combine a Credit Card Offer With EMI?
Sometimes, yes. But not automatically.
Some festive offers are available only on regular credit-card transactions, while others specifically apply to EMI transactions.
The product page or bank offer may say:
“10% instant discount on eligible credit cards” or “10% instant discount on eligible credit card EMI transactions.”
These are not necessarily the same thing.
So before selecting EMI, check: Is the bank discount valid on EMI?
This tiny line can make a big difference to your final price.
Popular Credit Cards for Online Shopping
Now let's get to the part many shoppers actually want to know:
“Which credit cards can be useful for online shopping?”
There isn't one universally “best” credit card. The right card depends on where you shop, how frequently you shop and which benefits you actually use.
Here are a few cards worth knowing about.
1. Flipkart Axis Bank Credit Card
If Flipkart is one of your regular shopping destinations, this is one of the obvious cards to know about.
The card currently offers 5% cashback on Flipkart and Cleartrip, while its published terms also provide 7.5% cashback on Myntra, subject to applicable quarterly limits.
The card also has a joining fee and annual fee under its current fee schedule, with the annual fee waiver linked to eligible annual spending.
Why shoppers may consider it:
- Useful for regular Flipkart shoppers
- Cashback benefits on selected partner platforms
- Can be relevant during Flipkart's festive sales
- Can provide additional value beyond a one-time sale discount
Flipkart's current Big Billion Days 2026 information also identifies the Flipkart Axis Bank Credit Card among cards that can provide sale-related benefits and early access.
Best suited for: Someone who frequently shops on Flipkart and can make enough use of the card's benefits to justify its applicable fees.
2. Amazon Pay ICICI Bank Credit Card
If you're more of an Amazon shopper, this one is worth knowing about.
The Amazon Pay ICICI Bank Credit Card currently has no joining or annual fee, according to ICICI Bank. Amazon Prime members can earn 5% back on eligible Amazon India purchases, while non-Prime cardholders can earn 3% on eligible Amazon purchases. The card also offers rewards on certain Amazon Pay partner merchants and other eligible spends.
One important catch:
Amazon says EMI purchases on Amazon do not earn the card's regular rewards.
So if you're buying an expensive smartphone on Amazon, don't assume that choosing EMI will automatically give you the same cashback as a normal purchase.
Best suited for: Regular Amazon shoppers who can benefit from Amazon Pay rewards and want a card with no joining or annual fee.
3. HDFC Bank Millennia Credit Card
This is another card that online shoppers may come across.
According to HDFC Bank's current information, the Millennia Credit Card offers 5% cashback on selected online merchants, including Amazon, Flipkart and Myntra, along with several other online platforms. It also offers 1% cashback on eligible other spends, with exclusions such as fuel, EMI, wallet, rent and government-related transactions.
This makes it interesting if your shopping isn't restricted to just one marketplace.
Best suited for: Someone who shops across multiple online platforms rather than sticking to only Amazon or Flipkart.
Which credit card should you get?
Don't get a credit card on the basis of a '10% OFF' pop up.
Ask yourself,
Do you shop mostly on Flipkart?
If yes, then a Flipkart focused card such as the Flipkart Axis Bank Credit Card could be a good buy.
Do you shop mostly on Amazon?
Then the Amazon Pay ICICI Bank Credit Card could be a better option.
Do you shop on multiple platforms?
Go for a more general cashback card like the HDFC Millennia.
Remember,
the right card depends on your spending habits, not the other way round.
Also, benefits and charges often change, so make sure to check the latest details with the issuing bank before applying.
Can You Use UPI and Still Get a Credit Card Offer?
Usually, not if the offer specifically requires a credit-card transaction.
For example, Axis Bank's published Flipkart offer terms state that certain offers are applicable to eligible Axis Bank card transactions but exclude Internet Banking and UPI transactions.
This is why simply having an eligible bank account isn't enough.
The payment method matters.
If the offer says: Eligible Axis Bank Credit Card you generally need to complete the qualifying transaction through the eligible card/payment route specified in the offer terms.
Frequently Asked Questions
What is a credit card in simple terms?
A credit card allows you to make purchases using a credit limit provided by the issuing bank and repay the amount later. If you do not clear the outstanding amount as required, interest and other charges may apply.
How do I use a credit card to get festive sale offers?
Check whether your card is eligible for the offer, confirm the minimum transaction value and maximum discount, select the eligible payment method at checkout and verify that the discount has been applied correctly before completing the purchase.
Can I get a discount on a smartphone using a credit card?
Yes, shopping platforms may run bank-specific offers on smartphones during festive sales. Eligibility depends on the specific sale, product, bank, card and payment method.
What is the difference between a credit card discount and cashback?
A credit-card discount generally reduces the eligible transaction amount according to the offer terms. Cashback is a reward returned to the customer after the qualifying transaction, according to the card or offer rules.
Is No-Cost EMI really free?
No-Cost EMI does not necessarily mean there are absolutely no costs associated with the transaction. RBI requires transparency around the principal, interest and upfront discount used to make an EMI “no cost.” Processing fees and applicable taxes may also need to be considered.
Which credit card is good for Flipkart shopping?
The Flipkart Axis Bank Credit Card is designed around benefits for Flipkart and selected partner spending, including cashback on Flipkart under its current terms. However, fees, cashback limits and benefits can change, so check the latest Axis Bank terms before applying.
Which credit card is useful for Amazon shopping?
The Amazon Pay ICICI Bank Credit Card is designed for Amazon and Amazon Pay users. ICICI Bank currently lists 5% back on eligible Amazon India purchases for Prime members and 3% for non-Prime cardholders, along with other benefits.
Can I use a credit card and EMI together?
Yes, credit-card EMI is a common payment option for eligible purchases. However, whether a particular festive bank offer can be combined with EMI depends on the specific offer terms.
Should I get a credit card just for a festive sale?
Usually, you should not apply for a credit card solely because a single sale offers a discount. Consider the card's fees, benefits, eligibility, spending pattern and long-term usefulness before applying.
Is it better to pay the full credit card bill or only the minimum amount?
If you can afford it, paying the full billed amount by the due date is generally preferable to carrying an unpaid balance, because unpaid balances can attract interest. RBI also warns customers about the long-term cost of making only minimum payments.

No comments posted yet. Be the first to express your thoughts!