Being a responsible adult in an Indian joint family is a full-time job. And during the festive season, my expenses could have their own festival of celebration!
All started well, Diwali was approaching and I thought that this year my expenses would be in control.
My younger brother asked me for the headphones he had eyed long ago. My sister sent me a link to the dress she had wanted to buy for a while. My cousins persuaded me to go shopping with them. The family needed to buy gifts for relatives and friends and, in general, I could not refuse them. I do not like seeing their cheerful and excited faces when they have to remain dissatisfied.
I want my siblings to enjoy big gifts, have happy parents who know that their children appreciate them, and above all, have nice holidays full of family traditions and joy. This is even more important for our joint family, where we all try to support each other.
After the holiday, the lights are gone, the sweets are finished, and the shopping bags are at home, it is time to look at your phone screen with a grin. But what are you going to do when you see your balance?
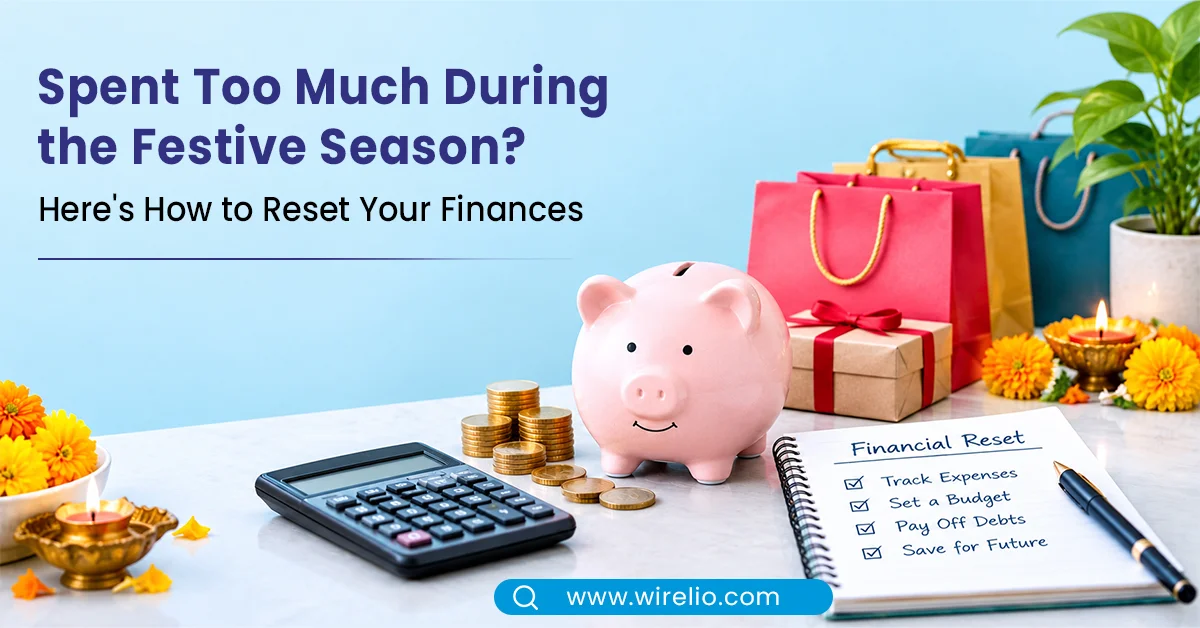
I understand you, and if you are in the same situation as I am, do not worry. Spending all the money during the holiday season is not a catastrophe. However, it is time to take some responsible steps to get your finances back on track.
Let’s take a look at how I handle my expenses after the holiday season and what steps I take to bring my finances back on track.
Step 1: Stop Spending on Autopilot
First of all, I try not to spend any more money on unnecessary things.
When I look at my bank balance after the holidays, I feel nervous. My first reaction is to spend even more money to compensate for the loss. No, I do not mean that I start shopping maniacally. My second reaction is to promise myself that I will never ever spend any money until the end of the month.
However, I understand that both reactions are too extreme, so I try to split them. For example, until my salary arrives, I make a list of all the things I need to buy. It is good if there are few things on the list, but if there are many, it means that I have lived too comfortably during the holidays and spent too much on non-essential items. But I still put off buying them for 24 or 48 hours.
This way, if I still need these things, I will have more time to find a cheaper alternative within my means. However, as for groceries, I am not putting them off, paying off credit cards, and buying medicine.
Step 2: Find Out Where the Money Actually Went
Second, I analyze all my purchases to see what exactly has happened to my money.
During the holidays, I thought that most of my expenses were due to gifts. But when I started analyzing the numbers, I realized that I spent most of my money on various purchases in different stores. What does it mean? It means that I bought a lot of unnecessary things instead of the gifts I wanted to buy.
I thought that I bought gifts for my family and friends, but it turned out that I was buying gifts for myself more often than I thought. Not only that, but I also ordered a lot of sweets, food, and drinks. All of this added up and led me to the current situation.
Step 3: Make a Post-Festival Budget That Works in Real Life
In a joint family, expenses don't always arrive one at a time. There's the monthly grocery bill, electricity, internet, family contributions, commuting costs and the occasional birthday or family gathering.
That's why I don't create an unrealistic budget that assumes nothing unexpected will happen.
Instead, I list my take-home income, fixed expenses, essential variable expenses, debt payments and savings. Whatever remains is the amount I can use for discretionary spending.
Step 4: Deal With Credit Card Bills Before They Grow
Here's where festive overspending can become particularly expensive.
If you used a credit card for gifts, electronics, clothes or travel, check the outstanding balance and payment due date as soon as possible.
My approach is to:
Pay at least the required amount by the due date to avoid late-payment consequences.
Aim to pay the full statement balance by the due date whenever possible.
Avoid taking on new discretionary purchases while clearing existing balances.
Check the interest rate and fees if I cannot pay the full balance.
Contact the card issuer if I anticipate difficulty making a payment.
Credit card interest can make an already expensive festive season cost even more. Paying only the minimum due may keep the account from becoming overdue, but it can leave a substantial balance accruing interest.
If you have multiple debts, list each balance, interest rate and minimum payment. Prioritise expensive debt while keeping up with the required payments on all accounts.
My rule: gifts should bring happiness, not months of unnecessary interest payments.
Step 5: Rebuild Your Emergency Fund—Even If You Start Small
Before the festive season, I might have been feeling quite proud of my savings. After buying gifts and contributing to family celebrations, though, that safety cushion can suddenly look much smaller.
The temptation is to wait until I have enough money to save a big amount again. But that can keep getting postponed.
Instead, I restart with an amount I can realistically afford.
It might be Rs. 500, Rs. 1,000 or Rs. 3,000 a month. The right amount depends on my income, debt obligations and essential expenses.
I keep this money separate from the account I use for everyday spending, so I'm less likely to dip into it for another online order.
Over time, the goal is to build an emergency fund that can help cover essential expenses during unexpected situations, such as a medical bill, job loss or urgent household repair.
If you have high-interest debt, balance emergency savings with repayment rather than following a rigid rule that ignores your circumstances.
The important thing is to restart the habit.
Step 6: Give Yourself a Temporary Shopping Break
My siblings are still sending me product links. Apparently, festive gifting season has a sequel!
But for a few weeks, I'm learning to distinguish between wanting something and needing it immediately.
Here are a few habits that help:
- Remove shopping apps from my home screen if I keep opening them out of habit.
- Unsubscribe from promotional messages that encourage impulse buying.
- Delete saved payment details where that helps me avoid accidental purchases.
- Use a 48-hour waiting period for non-essential purchases.
- Set a weekly discretionary spending limit and track it.
I don't believe in never enjoying my money. What's the point of working hard if I can't enjoy the occasional treat?
I just want to make sure that the next purchase doesn't interfere with my rent, household contribution, savings or debt repayment.
Step 7: Shop Smarter When You Need to Buy Something
A shopping break doesn't mean you can never buy anything again. Sometimes the household genuinely needs something, or a necessary purchase can't wait.
When that happens, I compare options instead of buying the first item I see.
For example, if we need a new mixer grinder for the family kitchen, I'll compare the capacity, motor power, warranty and final price across different listings. If I'm buying a gift for a sibling's birthday, I'll decide the budget first and then look for options within it.
A deal is only a good deal when the purchase fits your needs and budget.
This is also where a deal-discovery platform such as SearchMyDeals can help shoppers explore offers and compare shopping opportunities across online marketplaces before making a purchase decision. The idea isn't to buy more things just because discounts exist—it's to make planned purchases more thoughtfully.
My post-festival shopping checklist now looks like this:
Do I actually need this item?
Can I afford it without borrowing more?
Have I compared the final prices?
Is the seller reliable, and are the warranty and return terms clear?
Would waiting until next month make more financial sense?
Sometimes, the smartest deal is the one I decide not to buy.
Step 8: Plan for the Next Festival Before It Arrives
Here's a lesson I've learned the hard way: festive spending is rarely a surprise. The dates may move, but birthdays, anniversaries and annual festivals tend to return.
So, instead of scrambling for money next time, I now want to prepare in advance.
Suppose I expect to spend Rs. 12,000 on gifts and celebrations during the next festive season, and I have six months to prepare.
I can set aside Rs. 2,000 each month:
Rs. 12,000 ÷ 6 months = Rs. 2,000 per month.
That way, when the festival arrives, the money is already planned for rather than being pulled from my emergency fund or charged to a credit card.
I also create separate spending limits for:
Gifts for siblings and close family
Household celebrations and groceries
Clothes and personal shopping
Travel and family outings
Last-minute purchases
The amounts don't need to be perfect. They just need to be realistic enough that I can follow them.
And if I have a particularly expensive month, I can adjust the plan before the spending begins rather than after my bank balance starts looking scary.
Step 9: Don't Forget Your Own Financial Goals
When you're the elder sibling in a joint family, it's easy to put everyone else's needs ahead of your own.
You want to help your parents, make your siblings happy and contribute to family occasions. Those are meaningful things.
But your own future matters, too.
Maybe you're saving for further education, a vehicle, a home, a holiday or a long-term investment goal. Festive spending shouldn't automatically mean those plans disappear.
Once the immediate bills are under control, review your goals and resume your regular contributions where possible.
If you need to reduce contributions temporarily to handle essential expenses or expensive debt, make a deliberate plan for restarting them. Avoid taking investment risks or making rushed financial decisions just to recover money quickly.
Remember: being financially responsible isn't selfish. It helps you support your family more sustainably.
Step 10: Stop Feeling Guilty About Every Gift
This one is personal.
I still remember how excited my younger sister looked when she opened her gift. My brother's reaction was priceless, and the family celebrations gave us memories that will last far longer than the shopping receipts.
I don't regret making my siblings happy.
What I do regret is not deciding my spending limit beforehand.
There's a difference between spending thoughtfully on people you love and stretching your finances because you feel obligated to match everyone else's expectations.
Next time, I'll set a gift budget before shopping, look for meaningful options within it and remember that affection isn't measured by the price tag.
Sometimes, a thoughtful book, a handwritten note, a planned outing or something connected to a sibling's interests can mean just as much as an expensive gadget.
The goal isn't to stop being generous. It's to be generous without putting your financial stability at risk.
Final Thoughts: Your Wallet Can Recover, Brother!
The festive season reminds us that money can help create beautiful memories. But it also reminds us why planning matters.
As the elder brother in a joint family, I want to be someone my siblings can rely on. I want to contribute to our household, celebrate special moments and make the people I love feel valued.
I also want to pay my bills on time, build my savings and work towards my own goals.
Those things can exist together.
So, if you've spent more than you planned this festive season, don't panic, shame yourself or try to fix everything overnight. Review your expenses, make a workable budget, manage outstanding debt and start rebuilding your savings with whatever amount you can comfortably afford.
And next time my siblings send me a gift link, I'll still take a look.
I'll just check my budget before clicking Add to Cart.
Frequently Asked Questions (FAQs)
1. How can I reset my finances after the festive season?
Start by reviewing your spending, listing upcoming bills, creating a realistic monthly budget and prioritising outstanding debt. Pause non-essential shopping and restart savings at an affordable amount.
2. How do I recover from overspending during Diwali?
Review your transactions to identify where the money went, reduce discretionary purchases temporarily and make a plan for credit card balances or other debts. Avoid extreme budget cuts that make it difficult to cover essential expenses.
3. Should I use my savings to pay off festive-season credit card debt?
It depends on your interest rate, available cash and essential expenses. High-interest credit card debt can be costly, but avoid leaving yourself without money for immediate necessities or emergencies. Consider your overall financial situation before deciding how much savings to use.
4. How can I avoid overspending during the next festive season?
Set a total spending limit, create a gift list, assign budgets to different categories and start saving several months in advance. Comparing prices and avoiding impulse purchases can also help you stay within your limit.
5. How much should I save every month after overspending?
There is no single amount that suits everyone. Start with what you can realistically afford after essentials and required debt payments. Even a small, consistent contribution can help rebuild the habit of saving.
6. How can I manage family expectations while saving money?
Communicate your budget honestly and plan gifts around what you can comfortably afford. Thoughtful gifts and shared experiences can be meaningful without requiring expensive purchases.
7. What is the best way to rebuild an emergency fund after the festive season?
Set a realistic savings target, automate a manageable contribution if possible, and keep emergency money separate from everyday spending. Build the fund gradually while balancing any high-interest debt and essential expenses.
8. Should I stop all shopping after the festive season?
Not necessarily. Focus on pausing unnecessary purchases while continuing to pay for essentials and planned needs. The goal is to regain control of your spending, not to eliminate every enjoyable purchase.

No comments posted yet. Be the first to express your thoughts!